

Altman Z-Score Calculator: Predict Bankruptcy Risk
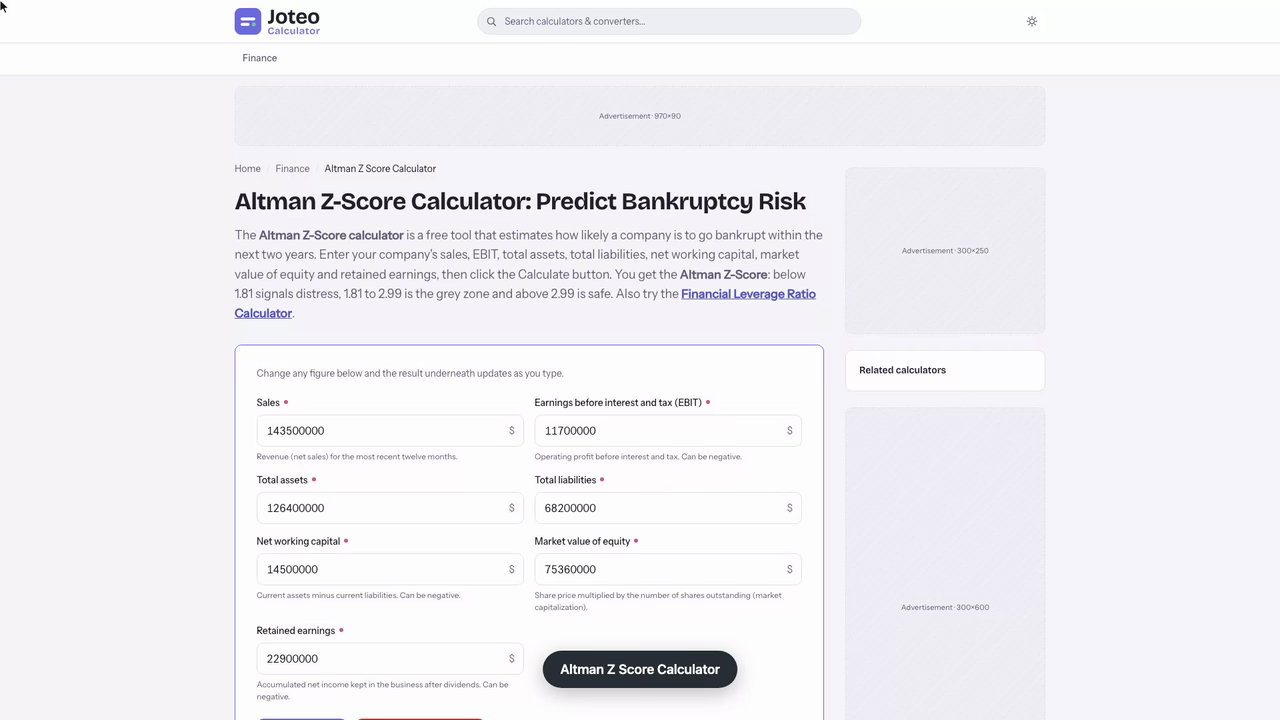
The Altman Z-Score calculator is a free tool that estimates how likely a company is to go bankrupt within the next two years. Enter your company's sales, EBIT, total assets, total liabilities, net working capital, market value of equity and retained earnings, then click the Calculate button. You get the Altman Z-Score: below 1.81 signals distress, 1.81 to 2.99 is the grey zone and above 2.99 is safe. Also try the Financial Leverage Ratio Calculator.
Altman Z Score Calculator inputs and result
Altman Z-Score
—
Table of contents
Who wrote and checked this page
Before you lend to, invest in, or ship goods on open account to a business, you want some evidence it will still be standing in two years. The Altman Z Score Calculator turns a handful of numbers from a firm's financial statements into a single Altman Z-Score, so you can see at a glance whether the business sits in the safe, grey or distress band for bankruptcy risk.
What the Altman Z-Score Measures
The Z-score is a bankruptcy prediction model published in 1968 by Edward Altman, then a young finance professor at New York University (NYU). He studied pairs of manufacturing firms, some that later failed and some that did not, and used multiple discriminant analysis to find the combination of financial ratios that best separated the two groups. The answer was a weighted sum of five measures, and it still works as a quick fiscal-fitness test for a business today.
What comes out is an estimate of the probability of failure within two years. A higher score means a stronger asset and earnings base; a lower score means the business looks more like the companies in Altman's sample that went on to fail. Because it compresses several dimensions of financial health into one number, lenders, suppliers, auditors and distressed investors use it as an early screen in credit analysis.
How the Altman Z-Score Equation Was Built
Most lending judgements used to be qualitative: an analyst read the accounts and formed a view. Altman's approach is a quantitative one. Discriminant analysis assigned each measure a weight (its coefficient) according to how well it told survivors from failures. The heaviest weighting went to operating profit on assets, which is why a sharp drop in earnings moves the result more than almost anything else. Treat the finished score as a company scoring tool, not a verdict: it tells you where to look harder, not what to conclude.
Why One Combined Score Helps
Any single ratio can mislead. A business with plenty of cash but no profits looks fine on one measure and dire on another. Blending five views of the same business stops you over-relying on one number and gives you a more balanced read of credit risk and long-run solvency.
The Altman Z-Score Formula and Its Five Components
The original version for publicly traded manufacturers multiplies five ratios by fixed coefficients and adds the results:
$$Z = 1.2X_1 + 1.4X_2 + 3.3X_3 + 0.6X_4 + 0.999X_5$$
Many sources round the last coefficient to 1.0 or 0.99; the difference only shows up in the second decimal place. Here is what each term measures, using TA as shorthand for total assets:

- X1 = WC ÷ TA. Working capital, meaning current assets minus current liabilities, over the asset base. This ratio tracks short-term liquidity: can the business pay the bills due this year?
- X2 = RE ÷ TA. Accumulated profits over the asset base. This shows accumulated profitability and how much the business has funded itself rather than through debt financing. Younger firms naturally score low here.
- X3 = EBIT ÷ TA. Earnings before interest and tax (operating income) over the asset base. It measures how well the assets produce operating profits, and it carries the largest coefficient, 3.3.
- X4 = MVE ÷ TL. Market value of equity (market capitalization, or share price × shares outstanding) over total liabilities. This captures leverage and the market's cushion: how far the stock could fall before liabilities exceed what shareholders' stake is worth, a direct read on downside risk.
- X5 = Sales ÷ TA. Revenue (net sales) over the asset base, better known as asset turnover. It measures how hard the assets work to generate business.
Each input is expressed as a share of the asset base (or, for X4, of what the business owes), so the z-score formula compares a small supplier and a multinational on the same scale.
Where Each Input Comes From
Five inputs come straight off the balance sheet: current items, TA, retained earnings and TL. Operating profit and revenue come from the income statement. Retained profits grow each year by net income minus dividends paid, so a business that pays out everything it earns will show a thin X2. The market value of the stock is the only market-based input, which is why the original version needs a listed business. Some analysts also strip intangible assets such as goodwill out of TA so that acquisition accounting doesn't dilute every ratio.
How to Use the Altman Z Score Calculator
The altman z-score calculator above follows the same seven-input layout used by most online tools, whether you work in an excel model or an online application. Pull the figures from the latest annual or quarterly report, keep every value in the same currency and units, then:
- Enter sales (revenue) for the most recent twelve months.
- Enter EBIT, operating profit before interest and tax.
- Enter total assets and total liabilities from the balance sheet.
- Enter net working capital, the short-term items netted against each other.
- Enter the market value of equity and retained earnings.
- Click the Calculate button and read the Z-score next to the zone thresholds below.
Some sites label this tool a z-score insolvency prediction calculator; the arithmetic is identical.
Altman Z-Score Calculation Example
Take a hypothetical listed maker of industrial pumps. Its latest accounts, in millions of dollars, show the figures in the table below. Its 9.6 million shares trade at $7.85, which puts the market value of the stock at $75.36 million. See also our Cash Flow per Share Calculator.
| Input or ratio | Value | Coefficient | Contribution to Z |
|---|---|---|---|
| Current assets / current liabilities | $41.8M / $27.3M | ||
| Total assets | $126.4M | ||
| Total liabilities | $68.2M | ||
| X1 = WC ($14.5M) ÷ TA | 0.1147 | 1.2 | 0.1377 |
| X2 = retained earnings ($22.9M) ÷ TA | 0.1812 | 1.4 | 0.2536 |
| X3 = EBIT ($11.7M) ÷ TA | 0.0926 | 3.3 | 0.3055 |
| X4 = MVE ($75.36M) ÷ TL | 1.1050 | 0.6 | 0.6630 |
| X5 = sales ($143.5M) ÷ TA | 1.1353 | 0.999 | 1.1341 |
| Z-score | 2.49 |
$$Z = 1.2(0.1147) + 1.4(0.1812) + 3.3(0.0926) + 0.6(1.1050) + 0.999(1.1353) = 2.49$$
A score of 2.49 puts the pump maker in the grey zone: not in immediate danger, but about 0.50 short of the 2.99 safe threshold. Notice where the score comes from. Asset turnover alone supplies 1.13 points, roughly 45% of the total, while X3 adds only 0.31 despite its big coefficient, because EBIT is just 9.3% of assets. That is the story a reviewer would focus on: a busy business with thin margins.

Run a quick stress test and the point becomes clearer. Cut EBIT by 30% to $8.19 million and hold everything else constant, and the z-score calculation drops to 2.40. It stays in the grey band, but the cushion above 1.81 shrinks from 0.68 to 0.59.
How to Interpret the Z-Score: Safe, Grey and Distress Zones
For the original public-manufacturer version, Altman's cut-offs split results into three bands. These are the benchmarks most calculators and textbooks use:
| Z-score range | Zone | What it signals |
|---|---|---|
| Above 2.99 | Safe zone | Low likelihood of bankruptcy on current figures |
| 1.81 to 2.99 | Grey zone | Moderate risk; the result alone is inconclusive |
| Below 1.81 | Distress zone | High probability of financial distress within the forecast window |
The middle band is sometimes called the gray area, and older write-ups split it further: a result between 2.7 and 2.99 puts a business on alert, a point where you proceed with caution, while the lower part of the band carries a real chance of default.

What Is a Good Altman Z-Score?
Higher is better. A reading above 3 is generally taken as a healthy company on these financial figures alone, and anything above 4 is comfortably clear. A good altman z-score for your purpose depends on context: a lender pricing a five-year loan wants more margin above 2.99 than a supplier weighing a single order.
Can the Z-Score Be Negative?
Yes. Negative working capital or operating losses make X1 or X3 negative, and a large enough loss drags the total below zero. In practice this is rare, because sales and the market value of the stock are usually large compared with those items, but a negative result points to a sharply higher probability of bankruptcy.
Vetting a New Customer with the Z-Score Calculator
A credit manager at a steel-tube distributor has a request on her desk: a small listed furniture maker wants its limit raised from $150,000 to $418,500, on net-60 terms, to cover a spring production run. The customer pays on time today, but a bigger exposure deserves a harder look, so she opens its latest quarterly filing and the exchange's quote page. You might also find our Return on Equity Calculator useful.
She keys in the figures exactly as reported, in millions:
- Sales, trailing twelve months: 61.28
- EBIT: 2.47
- Total assets: 52.64; total liabilities: 39.71
- Working capital: 18.37 current assets less 15.92 current liabilities, so 2.45
- Retained earnings: 3.18; market capitalization on the quote page: 14.05
The calculator returns an Altman Z-Score of 1.67. That sits 0.14 below Altman's 1.81 distress cut-off. Reading the breakdown explains why: asset turnover alone supplies 1.16 points, about 70% of the total, while operating return adds just 0.15 and the market-value cushion 0.21. The business is busy, but it earns very little on what it owns and carries almost three dollars of liabilities for every dollar of stock market value.
She works backwards before replying. Holding everything else fixed, EBIT would need to reach roughly $4.69 million, nearly double today's figure, to lift the score to 1.81. That isn't happening in one season. So she keeps the open limit at $150,000, offers the extra $268,500 against a standby letter of credit, and sets a reminder to rerun the Z-score the week the next quarterly filing posts.
Z-Score Model Variants for Private Firms and Non-Manufacturing Companies
The original formula needs a stock market valuation and was fitted on factory businesses, so Altman later re-estimated it for other cases. Using the wrong version is one of the most common errors, since the thresholds move with the coefficients:
| Version | Best for | Formula | Safe / distress cut-offs |
|---|---|---|---|
| Original Z | Publicly traded manufacturers | 1.2X1 + 1.4X2 + 3.3X3 + 0.6X4 + 0.999X5 | 2.99 / 1.81 |
| Z'-score | Private manufacturing firms | 0.717X1 + 0.847X2 + 3.107X3 + 0.420X4 + 0.998X5 (X4 uses book value) | 2.90 / 1.23 |
| Z''-score | Service and other non-industrial firms | 6.56X1 + 3.26X2 + 6.72X3 + 1.05X4 | 2.60 / 1.10 |
| Z''-EM | Emerging market issuers | 3.25 + the Z'' formula | 5.85 / 4.35 |
The Z''-score drops sales turnover entirely, because asset intensity varies so much between sectors that it would distort the result for retailers, software firms and service businesses. If you analyse private firms, swap the market value in X4 for book value and use the Z' thresholds instead.
Limitations of the Z-Score Model
The score is a screen, not a forecast you can bank on. Keep these limits in mind before acting on it:
- It was fitted on mid-century factories. Banks, insurers and other finance companies carry balance sheets it was never designed to read.
- Some healthy businesses look weak on paper: restaurants and grocers often run on supplier terms, so a low X1 can reflect efficient cash management rather than stress.
- Fast-growing, loss-making start-ups score badly by construction, even when funding is secure.
- Heavy fixed assets inflate total assets and pull down four of the five terms, and a low p/e multiple can compress X4 even when operations are sound.
- Thin net margin or operating margin trends show up only with a lag, because the inputs are backward-looking annual figures.
Treat a low reading as a red flag that calls for deeper work: read the notes on borrowing covenants, check refinancing dates, and look for signs of restructuring. Pair it with an interest coverage ratio, a debt-to-equity check and the bond market's credit spread before you draw a conclusion. The model has a solid record on corporate defaults in its home territory, but as a general rule of investing, no single metric should decide for you. Used alongside those checks, the z-score gives you a consistent, repeatable way to rank the financial stability of companies you're evaluating and to spot deterioration early, well before anyone starts defaulting on payments.
FAQs around Altman Z Score Calculator
1. What is a good Altman Z-Score?
For the original model used by this calculator, a score above 2.99 is in the safe zone, where the chance of bankruptcy is low. Between 1.81 and 2.99 is the grey zone, where the result is inconclusive, and below 1.81 is the distress zone, where the risk of failure within about two years is high.
2. How is the Altman Z-Score formula built?
Professor Edward Altman built it in 1968 with discriminant analysis, a statistical method that finds the weights that best separate companies that later failed from those that survived. The result is Z = 1.2 x (working capital / total assets) + 1.4 x (retained earnings / total assets) + 3.3 x (EBIT / total assets) + 0.6 x (market value of equity / total liabilities) + 1.0 x (sales / total assets).
3. What is EBIT?
EBIT means earnings before interest and taxes. It is roughly the company's operating income, and you can rebuild it as net income plus interest expense plus income taxes.
4. Can the Altman Z-Score be negative?
Yes. Negative net working capital, operating losses or accumulated deficits can pull the total below zero. It is uncommon, because sales and market value of equity are usually large compared with those items, but a negative score is a serious warning sign.
5. How do I find the market value of equity?
Multiply the current share price by the number of shares outstanding. This is the company's market capitalization, and it is why the original Z-score only works for publicly traded companies.
6. Can I use this calculator for a private or non-manufacturing company?
The original formula was fitted on public manufacturers. For private companies Altman's Z'-score uses book value of equity instead of market value, with cut-offs of 2.90 and 1.23. For service and other non-manufacturing firms the Z''-score drops sales from the formula and uses cut-offs of 2.60 and 1.10.
7. Should I rely on the Z-score alone?
No. Treat it as a screening tool. Banks and other financial companies, young loss-making firms and businesses that run on negative working capital can all score poorly while being sound, so confirm the result with other checks such as the interest coverage ratio and debt-to-equity ratio.
Report an issue with this page
Spotted a wrong result or unclear explanation? Report an issue or read our editorial policy.