

Liquid Net Worth Calculator: Cash You Can Reach Fast
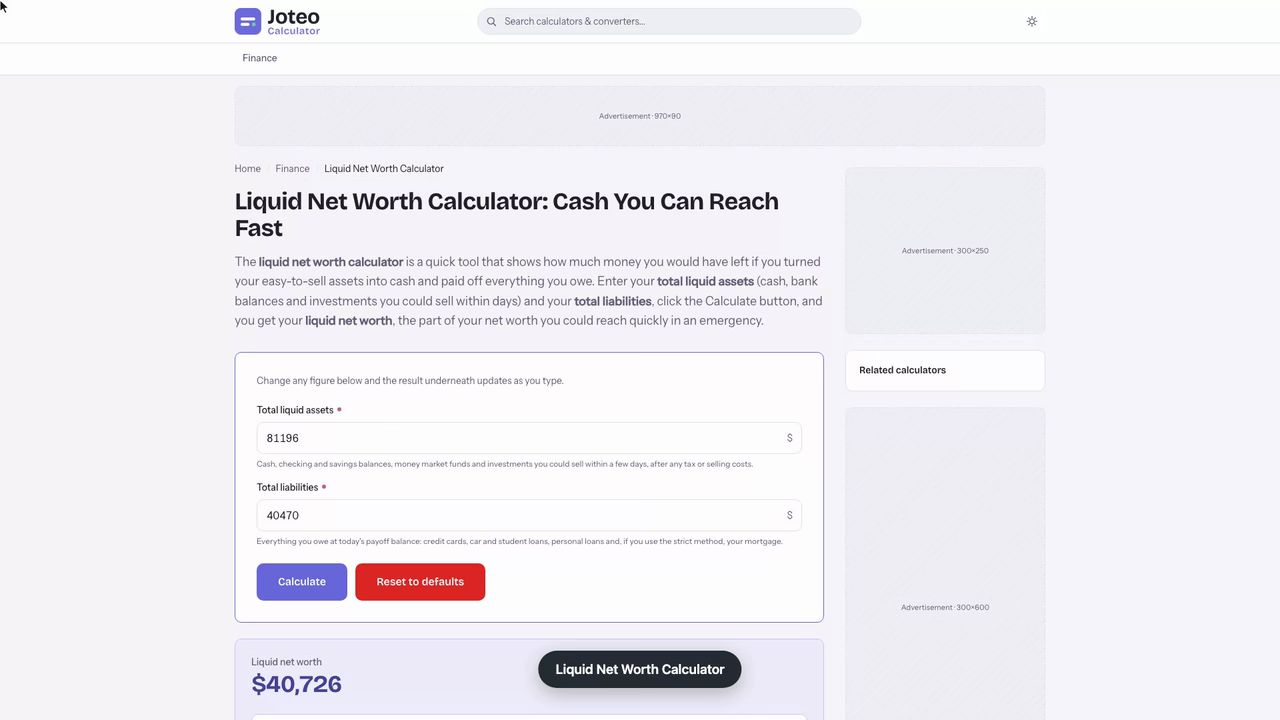
The liquid net worth calculator is a quick tool that shows how much money you would have left if you turned your easy-to-sell assets into cash and paid off everything you owe. Enter your total liquid assets (cash, bank balances and investments you could sell within days) and your total liabilities, click the Calculate button, and you get your liquid net worth, the part of your net worth you could reach quickly in an emergency.
Liquid Net Worth Calculator inputs and result
Liquid net worth
—
Table of contents
Who wrote and checked this page
Your bank app shows one balance, your retirement statement shows another, and neither tells you how much money you could actually lay your hands on this month. The liquid net worth calculator answers that question: enter the assets you could sell or withdraw quickly and everything you owe, and it returns the share of your net worth you could convert into cash and still keep after what you owe is settled. Knowing that figure sharpens your sense of affordability before you commit to a large purchase, a career change or a new credit line.
Liquid Net Worth Meaning and Definition
The liquid net worth definition is short: it is the value of everything you could turn into spendable money within a few days, minus every balance you owe. Ordinary net worth weighs what you own against your obligations across every holding, including a house and a pension. The liquid version keeps only the holdings that can be converted into cash without a long wait or a painful price cut, so it is always equal to or smaller than the headline figure.
Think of it as a stress-test number. A home, a car and a retirement balance can make a balance sheet look strong while leaving you with very little you could reach if your paycheck stopped. The liquid figure measures that gap. It is usually the first number a financial advisor asks about when a client mentions buying into a business, taking a sabbatical or leaving a salaried job for freelance work.
What Counts as a Liquid Asset
A liquid asset passes two tests: you can sell or withdraw it quickly, and doing so doesn't cost you a meaningful slice of its value. Money sitting in your bank accounts passes both. Publicly traded stocks and bonds, ETFs and mutual funds usually pass as well, because a sale normally reaches cash settlement within one business day. A thinly traded share whose market price jumps around fails the second test, since a rushed sale could lock in a loss that a patient seller would avoid.
Illiquid Assets and Partial Liquid Holdings
Illiquid assets take weeks or months to sell, or lose value when sold in a hurry: real estate, vehicles, jewelry, antiques, collectibles and a stake in a private company. Physical gold needs a buyer and an assay, and a pension normally pays out only from retirement age. Between the two extremes sit what some planners call partial liquid holdings: you can reach the money, but only after a cost.
- Workplace 401(k)s and a traditional IRA tapped before age 59½ usually trigger a 10% early withdrawal penalty on top of ordinary income tax.
- Roth accounts let you take back your contributions at any time, but earnings pulled out early can face tax and the same penalty.
- The cash value of a permanent life insurance policy is reachable, less any surrender charge in the policy's early years.
- Restricted stock units that are still unvested can't be sold at all until they vest.
- Bank fixed deposits and certificates can be broken early, usually in exchange for a reduced rate.
- Deferred annuities can often be cashed in, but surrender schedules and tax on the gains cut what you receive.
How to Calculate Your Liquid Net Worth
You can calculate liquid net worth in three steps, and the liquid net worth formula behind them is a single subtraction:
$$\text{Liquid net worth} = \text{Total liquid assets} - \text{Total liabilities}$$
In plain words it is assets minus liabilities, counting only the assets you could reach quickly and every obligation in full.
- Add up the balances you could reach within a week to get your total liquid assets: bank balances, money market funds and brokerage holdings.
- Add up everything you owe, at today's payoff figure, to get your total liabilities.
- Subtract liabilities from liquid assets. The result is your liquid net worth, and it can be positive, zero or negative.
Step 1: Add Up Total Liquid Assets
Use today's balances rather than monthly averages. Include your checking account, any savings account, a money market account, Treasury bills that mature within weeks, and the current market value of the holdings in your brokerage account. Leave out anything you would need a buyer, an appraiser or a court to turn into money. If you are unsure about an item, ask yourself whether the funds could be in your bank account by Friday without a significant loss. If not, it belongs in the illiquid column.
Step 2: Apply a Discount Factor to Partly Liquid Holdings
A holding you can sell only at a cost should count at less than its face value. Estimate what you would lose on a quick exit, such as capital gains on a taxable sale, trading commissions, or the taxes and 10% charge on a retirement plan tapped early, and cut the balance by that percentage. Bank balances need no haircut at all. Taxable investments with modest unrealized gains might lose 5-8%, while a tax-deferred plan emptied at 35 can easily lose a third of its value. Some people leave these holdings out of the calculation entirely; applying a haircut instead gives you a second, wider figure that is still honest about what you would receive.
Step 3: List Total Liabilities at Their Payoff Balance
Every balance you owe counts in full, because creditors expect to be repaid whatever you sell and however urgent your situation is, short of filing for bankruptcy. That covers credit cards, auto loans, student loans, a personal loan, a mortgage and any home equity line. Use the payoff balance quoted by each lender, which includes interest accrued since your last statement, rather than the figure printed on that statement.
Whether to count the home loan when you leave the house itself out is a judgment call. The strict approach counts it, because the obligation exists whether or not you sell. Others drop both sides, since you would only repay the home loan in full when you sell the property. Pick one method and use it every time you recalculate, so the numbers stay comparable from year to year.
Worked Example: A Liquid Net Worth Calculation
Say you are 34, rent your apartment, and hold the balances below. The cash accounts count at full value, the brokerage holdings take a 6% haircut for tax and trading costs, the workplace retirement plan takes a 35% haircut for the early-exit charge and tax, and the car is left out because it is illiquid.
| Holding | Balance | Discount factor | Liquid value |
|---|---|---|---|
| Checking account | $4,380 | 0% | $4,380 |
| High-yield savings | $21,650 | 0% | $21,650 |
| Money market fund | $9,200 | 0% | $9,200 |
| Brokerage holdings (index ETFs) | $48,900 | 6% | $45,966 |
| Workplace 401(k) | $83,500 | 35% | $54,275 |
| Car | $27,300 | Excluded | $0 |
| Total | $194,930 | $135,471 |
Your obligations are smaller and simpler:
| Obligation | Amount owed |
|---|---|
| Credit cards | $3,140 |
| Car loan | $14,860 |
| Student loan | $22,470 |
| Total | $40,470 |
Leaving the retirement plan out, your reachable assets come to $81,196 (the three bank balances plus the discounted brokerage holdings). Subtract the $40,470 you owe and your liquid net worth is $40,726. If you also count the 401(k) after its 35% haircut, reachable assets rise to $135,471 and the wider figure becomes $95,001. For comparison, your full balance sheet shows $194,930 of assets and a headline figure of $154,460, so only about a quarter of it is money you could spend this month without selling the car or raiding the retirement plan.

Liquid Net Worth Calculator Results: What Your Number Means
The result is a single dollar figure, but it answers a practical question: if your income stopped tomorrow, or an opportunity needed capital next week, how much could you put to work after clearing every balance you owe? A result of $40,726 says you could close all three obligations in the example today and still have more than $40,000 left in accessible money.

Positive, Zero and Negative Results
A positive result means your reachable money exceeds your obligations. A result of zero means they cancel out exactly: you could repay everything, but you would have nothing left. A negative result means you owe more than you could raise quickly. That is common early in a career, right after a home purchase, or while student balances are large, and it doesn't mean your finances are failing. It means your wealth is tied up in things that take time to sell, so a short-term shock would have to be covered with new borrowing.
Checking the Result Against an Emergency Fund
Planners commonly suggest keeping cash equal to three to six months of living expenses, often in a high-yield savings account so it earns something while it waits. In the example, spending runs $4,150 a month, which puts that target band at $12,450 to $24,900. The three bank balances total $35,230, about 8.5 months of spending, so this person already clears the top of the range and could move some of the surplus into longer-term investing. The calculator's own result goes a step further: $40,726 is what would remain after clearing every obligation, about 9.8 months of spending, so even after repaying everything this household still sits above the band.

Debt to Asset Ratio as a Cross-Check
Divide the $40,470 owed by the $194,930 of gross holdings and you get a ratio of 20.8%. A low ratio alongside a small liquid figure tells you the problem is access, not overborrowing: the money exists, but it is locked away. A high ratio alongside a small liquid figure is the more urgent combination, because the obligations are large relative to everything you hold.
Everyday Accounts and Their Liquid Value
Most households hold the same handful of account types, and each one lands in a predictable place between instantly spendable and locked away. Sorting yours before you use the calculator saves you from counting a house as spendable or forgetting a brokerage balance you rarely check.
Taxable Brokerage Balances and Deferred-Tax Plans
A taxable brokerage balance is close to fully liquid: you sell, the trade settles, and the only cost is the tax on any gain. A deferred-tax workplace plan is the opposite. The money is yours, but reaching it before retirement age usually means a charge plus income tax, which is why the example discounts it by 35% instead of 6%.
Retirement Accounts Before Age 59½
Many people treat retirement accounts as untouchable and leave them out of the calculation entirely. That gives the most conservative figure and suits a short-term cash question. Including them after a realistic haircut gives a better picture of your worst-case capacity, the money you could raise if every other option ran out.
Home, Car and Other Property
A house sold in a fire sale brings in less than its appraisal suggests, and agent fees plus closing costs take another slice. A car sold to a dealer as a trade-in or outright sale usually fetches noticeably less than a private sale would. Because neither can be sold in days at a fair price, both stay out of the calculation unless you have a specific plan to sell.
Testing a Franchise Application's Liquid Capital Rule with a Liquid Net Worth Calculation
A 41-year-old physiotherapist is filling in a franchise application for a small rehab studio. Page three of the form states the rule plainly: applicants must show at least $100,000 in liquid capital, verified from statements dated within 30 days. The house is off the table, and the franchisor's definition excludes retirement plans outright, so the figure has to come from ordinary accounts.
She pulls this morning's balances: $7,814 in checking, $38,265 in a high-yield deposit account, and a taxable index-fund position worth $71,340 that she bought for $52,740. Selling it would realize an $18,600 gain, and at a 15% long-term rate that costs $2,790, so she enters the fund at $68,550 rather than its screen value. On the other side she lists a $2,286 card balance and $11,947 left on her car, $14,233 in total.
She enters $114,629 as total liquid assets and $14,233 as total liabilities. The calculator returns a liquid net worth of $100,396.
That clears the franchisor's threshold by $396, which is 0.4% of the requirement. Before submitting, she reruns the numbers with the fund 5% lower, at $67,773. The gain shrinks to $15,033, the tax to $2,255, and the result drops to $97,364, $2,636 short. A routine market dip between today and the franchisor's statement check would sink the application.
- Result today: $100,396, $396 above the $100,000 minimum.
- Result after a 5% fund decline: $97,364, $2,636 below it.
So she holds the application for two statement cycles and sends her $3,100 monthly surplus straight into the deposit account. Two months later the same inputs, with the deposit account at $44,465, give $106,596, a 6.6% margin over the franchisor's line, and a 5% fund slip would still leave $103,564. That is the statement set she attaches.
Net Worth vs. Liquidity
Your headline figure is the right tool for tracking long-term financial progress: it captures home equity building up, retirement balances compounding and obligations shrinking. It moves slowly and it should. The liquid figure moves faster and answers a narrower question about the short term. Two people with identical net assets of $300,000 can be in very different positions if one holds it in a paid-off house and the other in index funds.
Good personal finance and financial planning use both numbers. The headline figure shows whether your investments and repayments are building wealth over decades; the liquid figure shows whether you could absorb a job loss, a medical bill or a sudden opportunity without selling something at the wrong moment.
How to Build More Liquidity
If your figure is small or negative, every change you make works through one of the calculator's two inputs: it either raises what you could reach quickly or shrinks what you owe. Knowing which one a move touches tells you whether the result will actually change.
- Pay down debt starting with high-interest debt such as a credit card balance. Paying it from a bank balance leaves the result flat on the day, but every later dollar of repayment that comes from income lowers the second input and lifts the figure by the same amount.
- Send a fixed slice of each paycheck to a separate bank account. That raises the first input directly, the way the franchise applicant's $3,100 monthly surplus moved her result from $100,396 to $106,596 in two months. A budgeting app helps you find the spending to redirect.
- Debt consolidation doesn't move the result when it happens, because the same balance simply moves to a new lender. It helps only if the lower rate frees up income that you then use to repay faster.
- Keep long-term contributions going. The goal is a figure that covers your short-term needs, not a balance sheet with nothing left compounding.
Recalculate every few months with the same method. A rising figure shows your safety margin growing even when the headline number barely moves.
FAQs around Liquid Net Worth Calculator
1. What is liquid net worth?
Liquid net worth is the value of the assets you could turn into cash quickly, such as bank balances and publicly traded investments, minus everything you owe. It shows how much money you could actually reach in a short time, unlike total net worth, which also counts your home, car and retirement plans.
2. How do I calculate my liquid net worth?
Add up your liquid assets to get total liquid assets, add up every debt at its payoff balance to get total liabilities, then subtract: liquid net worth = total liquid assets - total liabilities.
3. Can liquid net worth be negative?
Yes. If your total liabilities are larger than your total liquid assets, the result is negative. That means you couldn't repay all your debts quickly from accessible money alone. It's common early in a career or after buying a home.
4. What is my liquid net worth if my liquid assets equal my liabilities?
It's zero. You could repay everything you owe from your liquid assets, but you would have nothing left over afterwards.
5. Does a 401(k) count toward liquid net worth?
Usually not at full value. Withdrawing from a 401(k) before age 59 1/2 generally triggers a 10% penalty plus income tax, so many people leave it out or count it only after subtracting those costs.
6. Does liquid net worth include my car or house?
No, in most cases. Homes and vehicles take time to sell and often fetch less in a quick sale, so they're treated as illiquid assets and left out of the liquid assets total.
7. What is the difference between net worth and liquid net worth?
Net worth counts everything you own, including illiquid assets such as property, art and retirement accounts, minus what you owe. Liquid net worth counts only assets that can be turned into cash in a short time, so it is always equal to or smaller than net worth.
Report an issue with this page
Spotted a wrong result or unclear explanation? Report an issue or read our editorial policy.